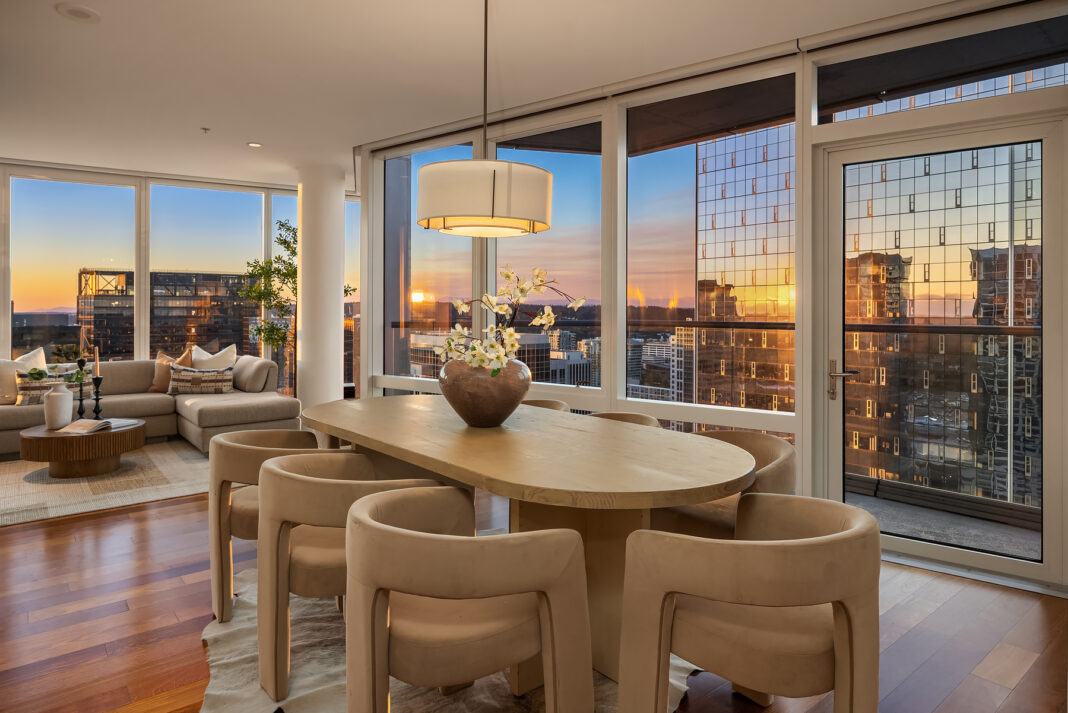

Downtown Bellevue’s condo market has cooled through the first half of 2026, with inventory climbing, closed sales falling, and average pricing seeing some erosion from a year ago. Here’s where the numbers stand at midyear and what buyers and sellers should expect heading into the second half of the year.
How does the market at midyear 2026 compare to where it started the year?
The year got off to a solid start, but activity slowed noticeably in the second quarter as geopolitical tension involving Iran and a round of local tech-sector layoffs weighed on buyer confidence. Neither factor is unique to condos, but both left a mark on downtown Bellevue’s resale condo market.
New construction sales trends have been harder to read, since many of those sales don’t get entered into MLS. I think it is fair to say that the new construction segment has been broadly slower, however, due both to properties being priced at a substantial premium versus resales and because developers tend to stay firmer on price since one discounted sale can set a precedent for other units remaining to sell in a building. It’s also been an active past few months for sales team moves between projects like Mari, Avenue and Park Row, typically a sign that a developer or sales team is looking for a fresh start after a stretch of slow sales activity.
The Park Row condominium project has so far bucked the slow sales trend with close to $100 million in sales over the past few months at its downtown park-front location, proof that compelling properties still draw buyers even in a slower market. It’s important to keep in mind though that sales like these also complicate the statistics since new construction presales often don’t close for another two or three years after they go under contract. That means today’s numbers understate market sales activity, while a future year will look artificially strong when those sales eventually close after construction of the building is complete.
Also worth noting: Avenue’s full rebrand to Nobu Estates and Residences, including a new 10,000-square-foot Nobu restaurant, caught much of the market off guard. I expect that to serve as strong third-party validation for the property going forward.
What role have interest rates played in this year’s slowdown?
The same geopolitical turmoil weighing on buyer psychology has also kept energy prices and inflation elevated, which has prevented mortgage rates from declining this year as had been widely anticipated. That’s added another headwind for buyers already navigating a slower market, with higher rates negatively affecting their purchasing power.

How does current active inventory compare to last year?
Inventory is up close to 50% compared with the first half of 2025. Measured in months of supply, we’re at roughly seven months, up from about five months a year ago. Markets tend to self-correct as sellers adjust price or pull listings, but inventory today is still higher than it’s been in some time.
How many condos have sold this year, and how does that compare to 2025?
Roughly 90 condos closed through the end of June, per MLS, compared with 112 during the same period in 2025, about 22 fewer sales.
What is the median sale price, and how does that compare to midyear 2025?
The median sales price is down about 17% year over year, and the average sales price is down about 13%. Looking only at resales, the decline is more moderate with the median down about 14% and the average down about 12%.
What is the average price per square foot, and why does that measure matter?
Price per square foot is my preferred pricing metric, since total price figures reflect the size of homes selling as much as their price. Across all sales, new construction and resale combined, price per square foot is down about 12% year over year. Isolating resales, which make up about the majority of what’s visible in MLS, that decline narrows to about 6%, a meaningful shift but well short of the double-digit swings the total price numbers suggest.
Are sellers getting close to asking price, or is there more room to negotiate?
There’s more room to negotiate this year. The average discount to list price is about 4%, compared with 2% during the same period last year. That figure likely understates the true discount, since MLS measures the discount to list against the most recent list price rather than the original one.
What is the average days on market right now?
About 60 days, up from 35 days over the same period last year. That statistic is based only on closed sales, so it likely understates how long homes are actually sitting in today’s slower market.
What should buyers and sellers expect for the second half of 2026?
I expect elevated inventory and a slower pace of sales to continue through the end of the year. The last significant wave of new listings will likely arrive in the weeks after Labor Day. Since sellers who don’t need to sell in the fall will often wait until early spring, I would anticipate early fall being the peak inventory window before options narrow into the holidays as properties sell or are removed from the market.
As for whether December listings mean better deals: I think it’s less about which listings are on the market at that time and more about how long they have been on by the time December rolls aroujnd. The best late-year opportunities tend to come from sellers who’ve already had a home listed for a number of months and are ready to be flexible.
What is your advice for buyers in the second half of 2026?
I recommend working with someone who is an expert in their neighborhood who has a good sense of market dynamics and can interpret data during shifting market conditions. Closed sales are backward looking by definition and a great agent can help you understand the market in real time. If you find a property that checks the right boxes, don’t be afraid to make an offer. Conditions can shift quickly, and buyer demand historically picks up early in the new year, often putting buyers back into competition for a much thinner pool of options than what we are seeing available today.